

Moody’s: Israel’s economy rocked by recession, politics
The worldwide slowdown in spending and a calcified political process have helped contribute to a slowdown in Israel’s economy – but things could be better soon
 Add ToI as a Preferred Source on Google
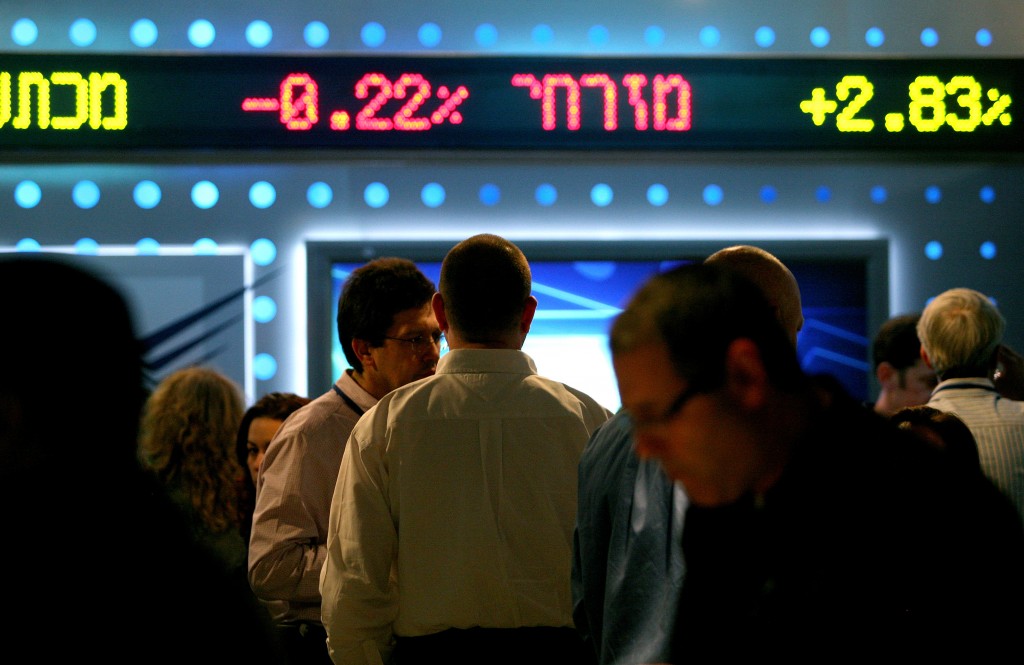
An economic slowdown that has pummeled the price of commodities, spending, and stock markets around the world has finally reached Israel, which until very recently has been one of the world’s most resilient economies, according to ratings agency Moody’s.
There is cause for hope, though. The agency expects things to bounce back in 2016, with greater income and spending likely to push the economy to better results. If spending doesn’t increase too much, Israel will be able to maintain its relatively low debt-to-GDP ratio (about 67% in 2014, one of the lowest among OECD countries) and this will ensure that Israel maintains its current sterling A1 bond rating.
Israel’s “resilient growth model, effective governance and steadily improving debt metrics” are positive signs for future growth, despite a current temporary dip in the economy, Moody’s said in its latest report on Israel, “Credit Analysis: Israel.”
“Israel’s economic growth has outpaced that of most advanced industrial economies over the past decade, supported by a competitive high-tech export sector, substantial spending on research and development and a well-educated labor force,” said Kristin Lindow, a Moody’s senior vice president and co-author of the report.
Since 2011, a gradually strengthening shekel has made it harder for Israel to export goods services, and with the recent economic turndown in both the developing and developed world, Israel’s trading partners have been buying less.
“After a relatively robust rebound from the global financial crisis, weaker demand from its trading partners and a strong shekel have weighed on Israel’s export sector since 2011 and have moderated the country’s growth,” the report said. “Both trends are likely to continue both this year and next.”
In addition, politics is playing a part in the country’s economic slowdown, said Moody’s.
“The last government dissolved in December 2014 after a short 20-month tenure and without finalizing a 2015 budget,” the report said. “The new government took six weeks to form after the March election, ultimately culminating in a coalition holding a very narrow one-vote majority. Partly as a consequence, the budget negotiation process was even more lengthy, leaving the government without a budget for much of 2015.”
Both those factors have led to uncertainty in the financial, business, and investment sectors, further contributing to a budding recession.
Even one of the economy’s brightest spots – its low debt-to-GDP ratio, the ratio between government debt and gross domestic product (lower indicates a lesser debt burden on taxpayers) – has been tarnished in recent years.
“While Israel is one of the few advanced countries that has a lower debt-to-GDP ratio now than before global financial crisis, slower growth and higher fiscal deficits have caused Israel’s debt burden to improve at a slower pace in the last three years,” the report said. As a result, “Moody’s forecasts that Israel’s 2015 budget deficit will come in at a below-target 2.5% of GDP.”
Indications are that the economy could pick up next year, however. “H:igher spending set for 2016 — such as civil servants’ salary increases — are likely to result in the deficit widening to 2.9% of GDP. In the context of the rating agency’s forecasts for nominal GDP growth, these deficits would be sufficiently low for the debt-to-GDP ratio to continue to decline.”
The higher spending would help revive demand and spending, which would be positive for the economy – but care must be taken, Moody’s cautioned. While some increased spending would be good, too much would be bad.
“A substantial further reduction in the government’s debt levels and a decline in regional geopolitical tensions would put upward pressure on Israel’s government bond rating,” said Moody’s, but “conversely, the government’s rating could face downward pressure if such tensions heightened, threatening Israel’s economic stability, or if the government’s commitment to fiscal discipline was to falter.”
The Times of Israel Community.